We believe a sea change may be underway in global equity markets, driven in part by the rising cost of money and elevated equity valuations, particularly in the United States.

With many equity valuation measures at or near historical extremes, and corporate earnings expectations increasingly ambitious, we believe investors may be assigning too little weight to the possibility that future earnings and investment returns could prove less favorable than currently anticipated.
Tweedy, Browne Funds Commentary, Q3 2026Global equity markets continued their seemingly inexorable advance during the third quarter, shrugging off persistent inflation, geopolitical turmoil, mounting government deficits, and concerns about the cost of capital. Buoyed by solid corporate earnings, continued enthusiasm surrounding artificial intelligence, and a seemingly insatiable appetite for risk, investors appeared largely willing to look past these gathering clouds. With US equity valuations already at historically elevated levels, the old adage that markets climb a wall of worry seemed particularly apt.
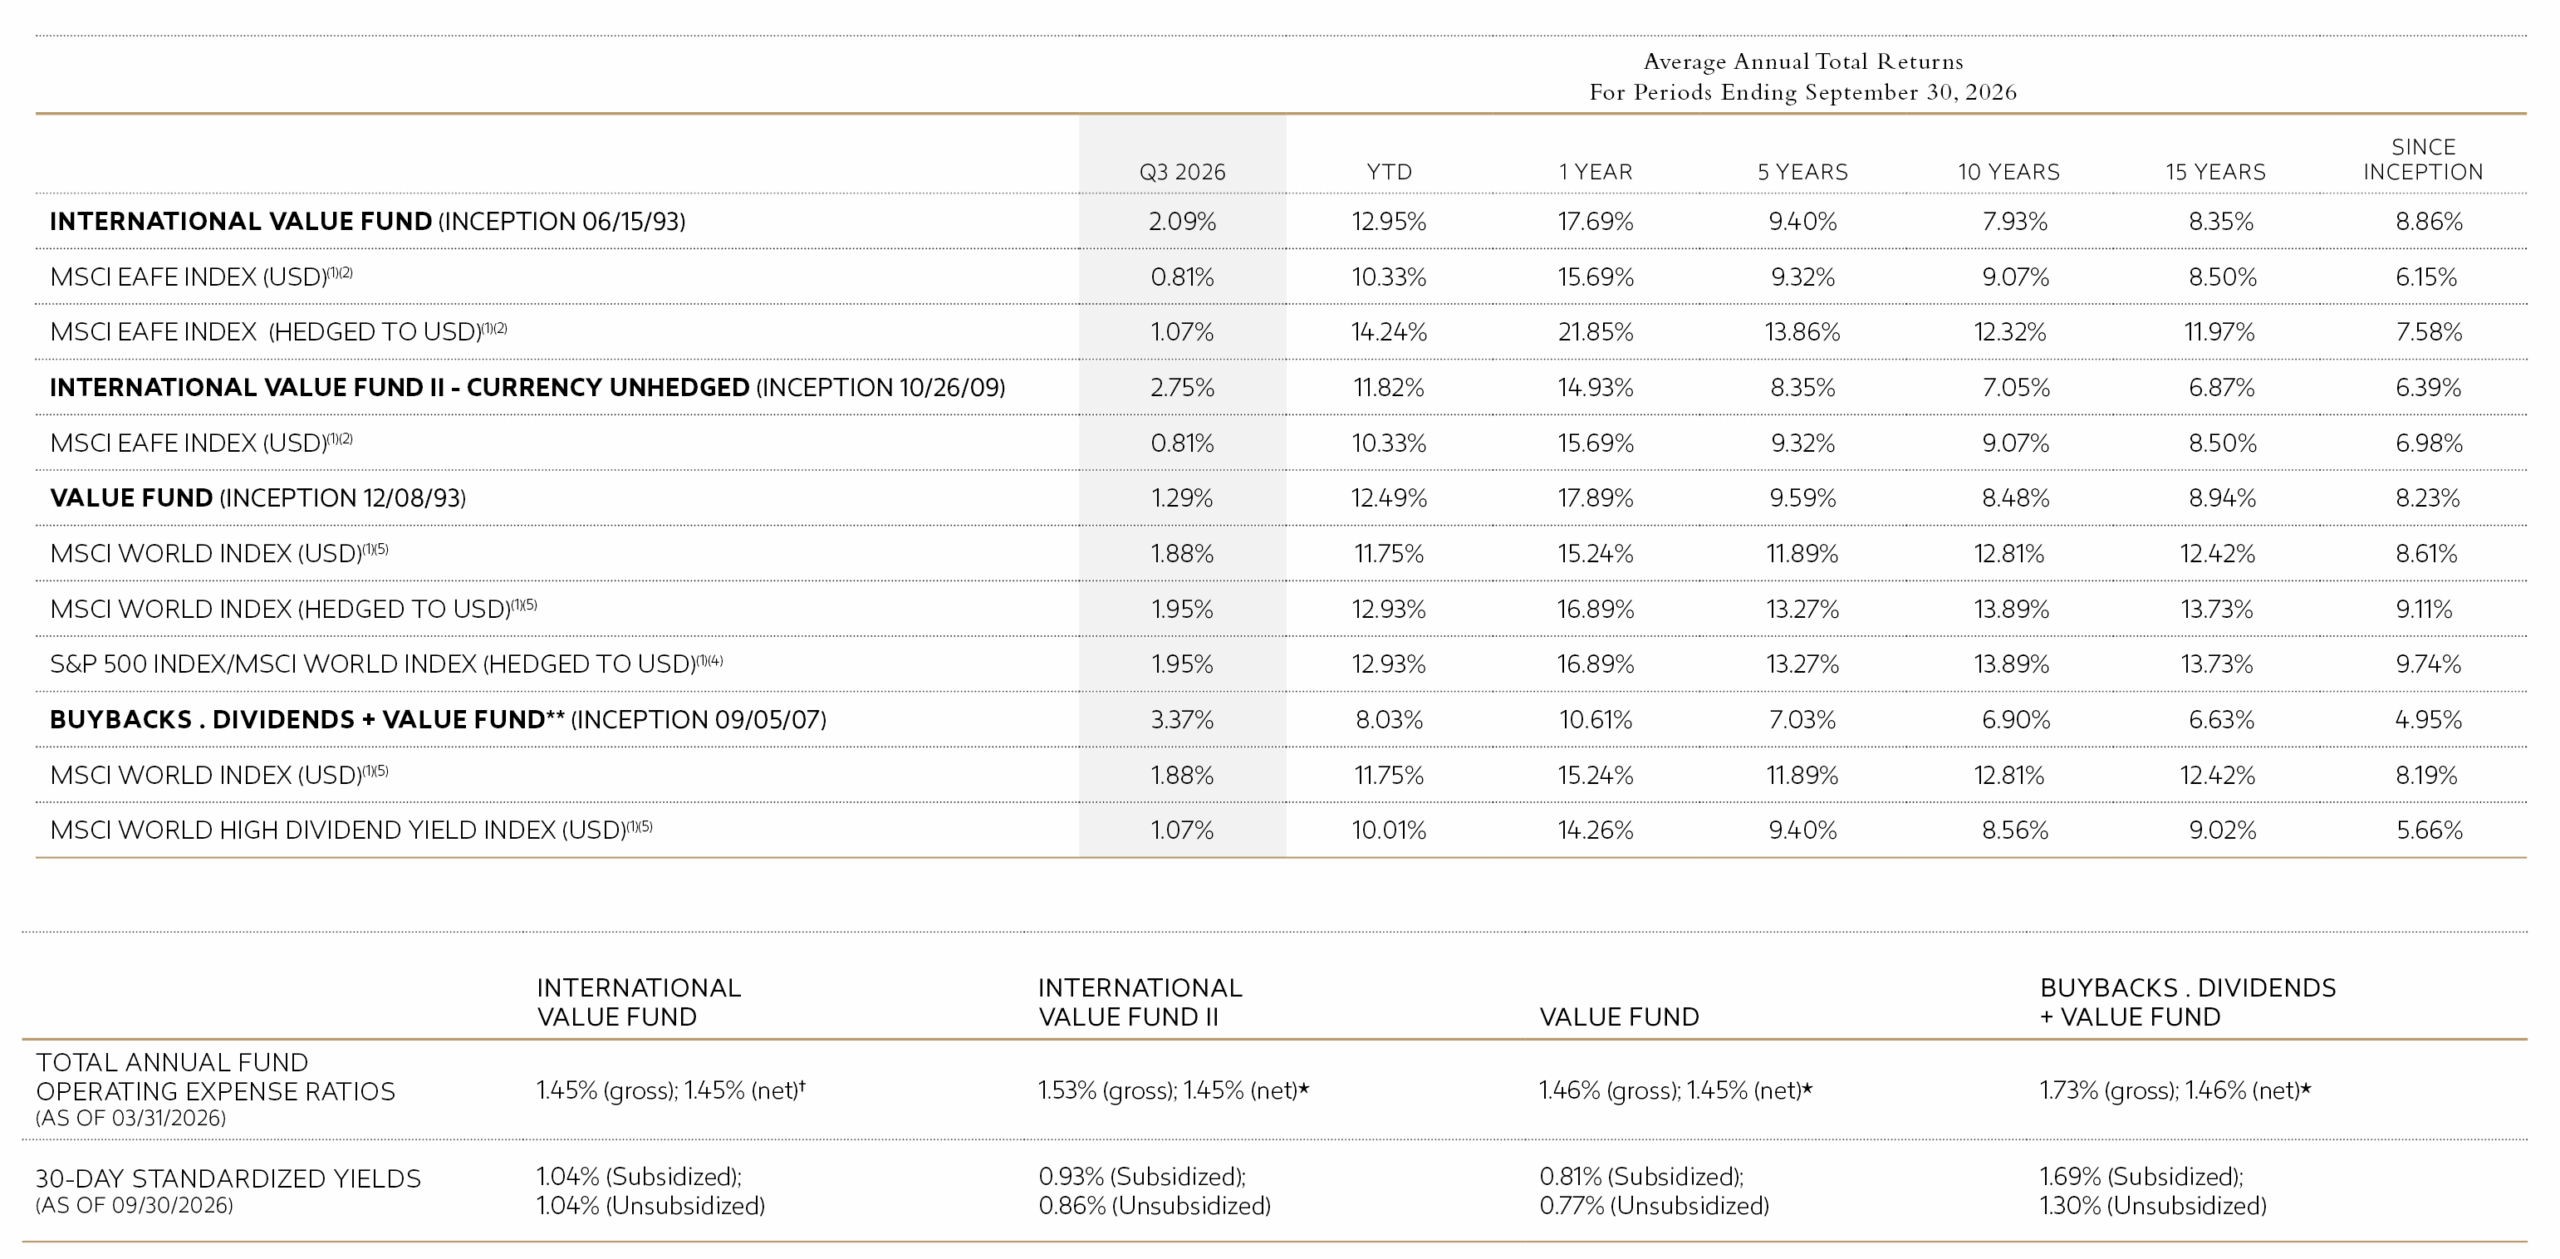
The performance data shown above represents past performance and is not a guarantee of future results. Investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be higher or lower than the performance data quoted. Please click here (TBGVX), here (TBCUX), here (TWEBX), and here (TBHDX) to obtain performance data that is current to the most recent month-end.
† Tweedy, Browne has voluntarily agreed, effective May 22, 2020 through at least July 31, 2027, to waive the International Value Fund’s fees whenever the Fund’s average daily net assets (“ADNA”) exceed $6 billion. Under the arrangement, the advisory fee payable by the Fund is as follows: 1.25% on the first $6 billion of the Fund’s ADNA; 0.80% on the next $1 billion of the Fund’s ADNA (ADNA over $6 billion up to $7 billion); 0.70% on the next $1 billion of the Fund’s ADNA (ADNA over $7 billion up to $8 billion); and 0.60% on the remaining amount, if any, of the Fund’s ADNA (ADNA over $8 billion). The performance data shown above would have been lower had fees not been waived during certain periods. The Adviser has agreed to waive the Fund’s management fee to the extent of any management fee charged in connection with the portfolio of the Fund’s assets that are allocated to an Affiliated Fund (as defined in the Fund’s Prospectus). Such waiver shall continue until July 31, 2027.
* Tweedy, Browne has voluntarily agreed, effective December 1, 2017 through at least July 31, 2027, to waive a portion of the International Value Fund II’s, the Value Fund’s and the Buybacks . Dividend + Yield Value Fund’s** investment advisory fees and/or reimburse a portion of each Fund’s expenses to the extent necessary to keep each Fund’s expense ratio in line with the expense ratio of the International Value Fund. (For purposes of this calculation, each Fund’s acquired fund fees and expenses, brokerage costs, interest, taxes and extraordinary expenses are disregarded, and each Fund’s expense ratio is rounded to two decimal points) The net expense ratios set forth above reflect this limitation, while the gross expense ratios do not. The International Value Fund II’s, Value Fund’s and Buybacks . Dividends + Value Fund’s performance data shown above would have been lower had fees and expenses not been waived and/or reimbursed during certain periods.
** Formerly known as Tweedy, Browne Worldwide High Dividend Yield Value Fund prior to May 27, 2026.
Please refer to footnotes (1) through (7) at the end of this commentary for descriptions of the Funds’ indexes.
The Funds do not impose any front-end or deferred sales charges. The expense ratios shown above reflect the inclusion of acquired fund fees and expenses (i.e., fees charged by the Adviser on Affiliated Funds and the fees/expenses attributable to investing cash balances in money market funds) and may differ from those shown in the Funds’ financial statements.
An encouraging development in 2026 has been broader market participation beyond the large-cap US technology companies that dominated returns in recent years. After more than a decade of extraordinary US market leadership, investors appear to be rediscovering the merits of attractively priced businesses outside the United States. We continue to find a wider assortment of opportunities in international markets, particularly among established companies with durable competitive positions, sound balance sheets, and meaningful free cash flow. That said, a rather narrow and familiar group of large U.S. technology companies once again led global equity returns during the quarter.
Against this mixed backdrop, all four Tweedy, Browne Funds produced positive absolute returns, ranging from 1.29% to 3.37%, and three outperformed their respective benchmarks. The International Value Fund and International Value Fund II–Currency Unhedged returned 2.09% and 2.75%, respectively, outpacing their international benchmark, the MSCI EAFE (in USD), which returned 0.81%. The Buybacks . Dividends + Value Fund returned 3.37%, exceeding the MSCI World Index’s (in USD) 1.88% return, as well as the MSCI World High Dividend Yield Index’s (in USD) 1.07% return. The Value Fund gained 1.29%, but trailed its benchmark, the MSCI World Index (in USD), which returned 1.88%.
*The performance data shown above represents past performance and is not a guarantee of future results. Investment return and principal value of an investment will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be higher or lower than the performance data quoted. Please click here (TBGVX), here (TBCUX), here (TWEBX), and here (TBHDX) to obtain performance data that is current to the most recent month-end.

We believe a sea change may be underway in global equity markets, driven in part by the rising cost of money and elevated equity valuations, particularly in the United States.
Please note that the individual companies discussed herein were held in one or more of the Funds during the quarter ended September 30, 2026, but were not necessarily held in all four of the Funds. Please refer to the full commentary (beginning of page 6) for selected purchase and sale information during the quarter and the Notes (on page 14) for each Fund’s respective holdings in each of these companies as of September 30, 2026.
In terms of what worked and didn’t work during the quarter, the Funds benefited from strength in a number of their industrial and information technology holdings. Machinery companies, IT service businesses, and select banks were among the more significant contributors. CNH Industrial, Computacenter, Aalberts, Trelleborg, and DHL contributed positively across all four portfolios. TotalEnergies and Rubis also contributed, reversing their negative contributions of the previous quarter.
Within Information Technology, strong results from IT service companies helped to offset weakness elsewhere in the sector. Computacenter and Capgemini contributed positively across the Funds, while Alten was a particularly significant contributor. Conversely, Samsung Electronics was a significant detractor. Among financial holdings, United Overseas Bank contributed across all four portfolios, while Hana Financial Group and DBS Group were additional sources of strength.
Health Care, particularly biotech, weighed negatively on results, with Ionis Pharmaceuticals accounting for a substantial portion of the weakness. Results within the sector were far from uniform, however. Sysmex, bioMérieux, and Fresenius contributed positively, helping to offset declines elsewhere. Outside Health Care, Johnson Service Group, Nestlé, Auto Trader, and select chemical holdings weighed on results.
The Buybacks . Dividends + Value Fund had a somewhat different experience. Its holdings in CNH Industrial, Computacenter, DBS Group, Rubis, and Sega Sammy were among its more significant contributors. Its more significant detractors included Johnson Service Group, Nestlé, Megacable, and Suzuken.
From a geographic standpoint, holdings in France and the UK were important sources of positive returns across the Funds. The French contribution reflected strength in a number of service businesses, together with Rubis and, where held, TotalEnergies. Computacenter and Pets at Home were among the contributors in the UK, although weakness in Johnson Service Group and Auto Trader tempered the gains. Singapore holdings also contributed positively. In contrast, US holdings weighed on results, particularly as a result of the decline in Ionis.
A list of selected newly established positions, including additions, sales, and trims of existing positions for each Fund, is included with each Fund’s portfolio page, in the full commentary (beginning of page 6).
During the quarter, we established several new positions and added selectively to an existing holding, while trimming or selling other investments. These purchases spanned a range of businesses and markets, reflecting our continuing search for opportunities where the relationship between price and underlying value appears attractive.
Among the new positions were Aptiv, the automotive technology and components supplier; LVMH, the French luxury goods group; Minth Group, a manufacturer of automotive exterior and structural components; Puregold Price Club, a Philippine supermarket operator; and Toyota Motor. We also initiated or added to the position in an undisclosed Taiwanese manufacturer of composite products used in sporting goods and other applications. At purchase, we believed these companies were trading at discounts to conservative estimates of their intrinsic value, were financially strong, and had attractive prospects for long-term growth.
On the sell side, we trimmed Computacenter following its strong advance and eliminated Teleperformance from two portfolios after it contributed positively during the quarter. We also reduced or eliminated positions in Transcosmos and Alliance Global Group. Other activity included sales of Kuraray, Adris Grupa, and LX Holdings, and reductions in holdings such as UniFirst, Vertex Pharmaceuticals, Pets at Home, and Okamoto Industries.
As mentioned in the last two quarters, the investment strategy for the newly renamed Tweedy, Browne Buybacks . Dividends + Value Fund (formerly the Worldwide High Dividend Yield Value Fund) was modestly adjusted to emphasize investment in companies that pay an attractive dividend and/or have initiated share buybacks when their shares trade at discounts to underlying value. Our assessment of undervaluation incorporates proprietary combinations of numerical value-oriented investment characteristics, a value score, and qualitative analysis. The Fund no longer requires an above-average dividend.
The expanded mandate continued to broaden the Fund’s opportunity set during the quarter. New positions included Albertsons, the US supermarket operator; Astra International, the Indonesian conglomerate; Bangkok Life Assurance, the Thai life insurer; Hikma Pharmaceuticals; Jumbo, the Greek retailer; Springer Nature, the academic publisher; and Toyo Tire. The Fund also established a few new positions, including Minth Group and Toyota Motor. These purchases reflect the Fund’s broader focus on undervaluation coupled with dividends and/or share repurchases.
The Fund also trimmed several existing holdings, including Computacenter, DBS Group, DHL, KBC Group, Nestlé, Novartis, Roche, and Safran. Positions in Teleperformance, Haitian International, Hang Lung Group, LG Corp, LX Holdings, Metropolitan Bank & Trust, Transcosmos, Truist Financial, Uni-President China, and Western Union were eliminated.
As always, our purchase and sale decisions remain grounded in an assessment of price relative to underlying business value, with an emphasis on financial strength and the long-term prospects of the companies in which we invest.
ETF share classes. As we have previously reported, our application for exemptive relief to establish ETF share classes for our Funds was approved by the Securities and Exchange Commission (“SEC”), and we are working diligently to help make these new share classes available to shareholders in the coming months. In June, we filed a Preliminary Prospectus and Statement of Additional Information for these new share classes which are currently under review by the SEC. We remain excited about the opportunity, and we will continue to keep you apprised of our progress.
We believe a sea change may be underway in global equity markets, driven in part by the rising cost of money and elevated equity valuations, particularly in the United States. If we are right, the years ahead could look considerably different from the recent past. Higher interest rates should, in our view, restore some of the relevance of price-sensitive investing after a prolonged period in which investors were often rewarded for paying almost any price for anticipated growth. With many equity valuation measures at or near historical extremes, and corporate earnings expectations increasingly ambitious, we believe investors may be assigning too little weight to the possibility that future earnings and investment returns could prove less favorable than currently anticipated.
The extraordinary capital spending associated with artificial intelligence also raises questions about the ultimate economic returns on these investments. While AI holds considerable promise for improving productivity, it remains uncertain whether the enormous sums being committed to infrastructure will generate satisfactory returns on capital, particularly as competition intensifies and some historically asset-light technology businesses become increasingly capital intensive. At the same time, elevated levels of margin borrowing and growing investor enthusiasm for speculative investment products suggest a degree of complacency about downside risk. None of these developments necessarily signals an imminent market reversal, but collectively they give us reason for caution.
Despite these concerns, we continue to find attractive opportunities in global equity markets, particularly among established businesses with durable competitive advantages, strong balance sheets, and the ability to generate meaningful free cash flow. Should today’s exuberance eventually give way to a more discriminating, price-sensitive market environment, we believe our Funds are reasonably well-positioned to weather the resulting volatility and potentially gain ground on their benchmarks. Conversely, should animal spirits continue to propel equity prices higher, we expect to participate in the advance, although perhaps not to the same extent as more aggressively positioned growth-oriented portfolios. We are comfortable with that trade-off. Our objective remains to compound our shareholders’ capital at attractive rates over time while remaining mindful of the risk of permanent capital loss.
We sincerely appreciate your investment in our Funds and thank you for your continued trust and confidence.
Roger R. de Bree, Andrew Ewert, Frank H. Hawrylak, Jay Hill, Thomas H. Shrager, John D. Spears, Robert Q. Wyckoff, Jr. | Investment Committee* | Tweedy, Browne Company LLC
October 2026
* Each member of the Investment Committee is a current investor in one or more of the Funds.
(1) Indexes are unmanaged, and the figures for the indexes shown include reinvestment of dividends and capital gains distributions and do not reflect any fees or expenses. Investors cannot invest directly in an index.
(2) The MSCI EAFE Index is a free float-adjusted, market capitalization weighted index that is designed to measure the equity market performance of developed markets, excluding the US and Canada. The MSCI EAFE Index (in USD) reflects the return of the MSCI EAFE Index for a US dollar investor. The MSCI EAFE Index (Hedged to USD) consists of the results of the MSCI EAFE Index hedged 100% back into US dollars and accounts for interest rate differentials in forward currency exchange rates. Results for each index are inclusive of dividends and net of foreign withholding taxes.
(3) Inception dates for the International Value Fund, International Value Fund II, Value Fund and Buybacks . Dividend + Yield Value Fund are June 15, 1993, October 26, 2009, December 8, 1993, and September 5, 2007, respectively. Prior to 2004, information with respect to the MSCI EAFE and MSCI World Indexes used was available at month end only; therefore, the since-inception performance of the MSCI EAFE Indexes quoted for the International Value Fund reflects performance from May 31, 1993, the closest month end to the International Value Fund’s inception date, and the since inception performance of the MSCI World Index quoted for the Value Fund reflects performance from November 30, 1993, the closest month end to the Value Fund’s inception date. For International Value Fund, information with respect to the Morningstar Foreign Stock Fund Average or the Foreign Stock Fund Average (see note 6 below) are available at month end only; therefore, the closest month end to the inception date of the International Value Fund, May 31, 1993, was used.
(4) The S&P 500/MSCI World Index (Hedged to USD) is a combination of the S&P 500 Index and the MSCI World Index (Hedged to USD), linked together by Tweedy, Browne, and represents the performance of the S&P 500 Index for the periods 12/08/93 – 12/31/06 and the performance of the MSCI World Index (Hedged to USD) beginning 01/01/07 and thereafter (beginning December 2006, the Fund was permitted to invest more significantly in non-US securities). The S&P 500 Index is a market capitalization weighted index composed of 500 widely held common stocks that assumes the reinvestment of dividends. The index is generally considered representative of US large capitalization stocks.
(5) The MSCI World Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of developed markets. The MSCI World Index (in USD) reflects the return of this index for a US dollar investor. The MSCI World Index (Hedged to USD) consists of the results of the MSCI World Index with its foreign currency exposure hedged 100% back into US dollars. The index accounts for interest rate differentials in forward currency exchange rates. The MSCI World High Dividend Yield Index reflects the performance of equities in the MSCI World Index (excluding REITs) with higher dividend income and quality characteristics than average dividend yields that are both sustainable and persistent. The index also applies quality screens and reviews 12-month past performance to omit stocks with potentially deteriorating fundamentals that could force them to cut or reduce dividends. The MSCI World High Dividend Yield Index (in USD) reflects the return of the MSCI World High Dividend Yield Index for a US dollar investor. Results for each index are inclusive of dividends and net of foreign withholding taxes.
(6) Since September 30, 2003, the Foreign Stock Fund Average is calculated by Tweedy, Browne based on data provided by Morningstar and reflects average returns or portfolio turnover rates of all mutual funds in the Morningstar Foreign Large-Value, Foreign Large-Blend, Foreign Large-Growth, Foreign Small/Mid-Value, Foreign Small/Mid-Blend, and Foreign Small/Mid-Growth categories. Funds in these categories typically invest in international stocks and devote no more than 20% of assets to US equity markets. These funds may or may not be hedged to the US dollar, which will affect reported returns. References to “Foreign Stock Funds” or the “Foreign Stock Fund Average” that predate September 30, 2003 are references to Morningstar’s Foreign Stock Funds and Foreign Stock Fund Average, respectively, while references to Foreign Stock Funds and the Foreign Stock Fund Average for the period beginning September 30, 2003 refer to Foreign Stock Funds and the Foreign Stock Fund Average as calculated by Tweedy, Browne.
(7) Since April 28, 2017, the Global Stock Fund Average is calculated by Tweedy, Browne based on data provided by Morningstar, and reflects average returns or portfolio turnover rates of all mutual funds in the Morningstar Global Large Stock (including Global Large Value, Global Large Growth, and Global Large Blend categories) and Global Small/Mid Stock categories. Prior to April 28, 2017, the Global Stock Fund Average was calculated by Morningstar. Funds in these categories typically invest in stocks throughout the world while maintaining a percentage of their assets (normally 20% – 60%) invested in US stocks. These funds may or may not be hedged to the US dollar, which will affect reported returns. References to “Global Stock Funds” or the “Global Stock Fund Average” that predate April 28, 2017 are references to Morningstar’s Global Stock Funds and Global Stock Fund Average, respectively, while references to Global Stock Funds and the Global Stock Fund Average for the period beginning April 28, 2018 refer to the Global Stock Funds and Global Stock Fund Average as calculated by Tweedy, Browne.
The Funds are actively managed, unlike the indexes, and consist of securities that vary widely from those included in the indexes in terms of portfolio composition, country and sector allocations, and other metrics. Hedged indexes are included to illustrate how the stocks that are components of the hedged indexes would have performed in their local currencies for a US dollar investor. The hedged indexes are fully nominally hedged on a monthly basis, whereas the International Value Fund and the Value Fund hedge their perceived currency exposure only where practicable. Tweedy, Browne applies a different hedging methodology than the hedged indexes. Index results are shown for illustrative purposes only.
The performance results reflected above are over the course of many years and reflect multiple market cycles and varying geopolitical, market and economic conditions. Past performance is no guarantee of future results.
Content reproduced from Morningstar is ©2026 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar and/or its content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. Past performance is no guarantee of future results.
As of September 30, 2026, the International Value Fund, International Value Fund II, Value Fund, and Buybacks . Dividend + Yield Value Fund had each invested the following percentages of its net assets, respectively, in the following portfolio holdings:
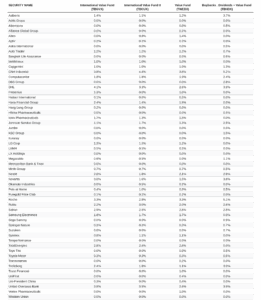
The above listed portfolio holdings reflect the Funds’ investments on the date indicated and may not be representative of the Funds’ current or future holdings. Selected Purchases & Sales illustrate some or all of the largest purchases and sales made for each Fund during the preceding quarter and may not include all purchases and sales. Some “undisclosed” names may have been withheld where disclosure may be disadvantageous to a Fund’s accumulation or disposition program.
All investing involves the risk of loss, including the loss of principal. Current and future portfolio holdings are subject to risk. The securities of small, less well-known companies may be more volatile than those of larger companies. In addition, investing in foreign securities involves additional risks beyond the risks of investing in securities of US markets. These risks which are more pronounced in emerging markets, include economic and political considerations not typically found in US markets, including currency fluctuation, political uncertainty and different financial standards, regulatory environments, and overall market and economic factors. Force majeure events such as pandemics and natural disasters are likely to increase the risks inherent in investments and could have a broad negative impact on the world economy and business activity in general. Value investing involves the risk that the market will not recognize a security’s intrinsic value for a long time, or that a security thought to be undervalued may in fact be appropriately priced when purchased. Dividends are not guaranteed, and a company currently paying dividends may cease paying dividends at any time. Diversification does not guarantee a profit or protect against a loss in declining markets.
Although the practice of hedging perceived foreign currency exposure, where practicable, utilized by the International Value Fund and Value Fund reduces the risk of loss from exchange rate movements, it also reduces the ability of the Funds to gain from favorable exchange rate movements when the US dollar declines against the currencies in which the Funds’ investments are denominated and may impose costs on the Funds. As a result of practical considerations, fluctuations in a security’s prices, and fluctuations in currencies, a Fund’s hedges are expected to approximate, but will generally not equal, the Fund’s perceived foreign currency risk.
Stocks and bonds are subject to different risks. In general, stocks are subject to greater price fluctuations and volatility than bonds and can decline significantly in value in response to adverse issuer, political, regulatory, market or economic developments. Unlike stocks, if held to maturity, bonds generally offer to pay both a fixed rate of return and a fixed principal value. Bonds are subject to interest rate risk (as interest rates rise bond prices generally fall), the risk of issuer default, issuer credit risk, and inflation risk, although US Treasuries are backed by the full faith and credit of the US government.
Investors should refer to the prospectus for a description of risk factors associated with investments in securities which may be held by the Funds. Investing involves the risk of loss, including the loss of principal. There is no assurance that a Fund will achieve its investment objective.
This commentary contains opinions and statements on investment techniques, economics, market conditions and other matters. There is no guarantee that these opinions and statements will prove to be correct, and some of them are inherently speculative. None of them should be relied upon as statements of fact. The views expressed herein represent the opinions of Tweedy, Browne Company LLC as of the date of this commentary, are not intended as a forecast or a guarantee of future results, or investment advice and are subject to change without notice.
Tweedy, Browne International Value Fund, Tweedy, Browne International Value Fund II – Currency Unhedged, Tweedy, Browne Value Fund, and Tweedy, Browne . Buybacks . Dividends + Value Fund are distributed by Quasar Distributors, LLC.
This material must be preceded or accompanied by a current prospectus for Tweedy, Browne Fund Inc. Click here for a copy of the Funds’ prospectus. You should consider the Funds’ investment objectives, risks, charges and expenses carefully before investing. The prospectus contains this and other information about the Funds. The prospectus should be read carefully before investing.
You are navigating from Tweedy U.S. Funds to {{ TARGET_SITE }}.